What Crypto Value Actually Means
Crypto value isn't one number. It can mean the price of a token, the economic activity on its network, how useful the resource it provides is, how much liquidity buyers and sellers have, and what people expect about future adoption. These things are related but they're not the same. A cryptoasset can get value from different roles in its protocol. It can be a way to exchange value, a store of value, and a unit of account. Bitcoin's network tries to do all three. A stablecoin gets practical value by reducing the price swings you see with other cryptoassets. A network token might get value from providing blockspace, validating transactions, securing a protocol, or capturing activity across an app ecosystem. The value also depends on regulation, custody, security, political influence, and whether people actually use the product.
Different parts of the market look at different value drivers. A valuation model might focus on monetary velocity, transaction volume, adoption, and supply. A market analysis might look at the difference between valuable apps and abundant blockspace. A stablecoin analysis might focus on payments, remittances, liquidity, and regulation. A security analysis might look at hacks, collateral failures, liquidity shortages, and whether users can withdraw funds. These approaches describe different parts of the same value structure.
Early Attempts to Value Bitcoin
In 2017 Chris Burniske wrote about a growing effort among crypto market participants to build frameworks for valuing cryptoassets. For years some people called Bitcoin valueless or compared it to tulips. The new interest in valuation was an attempt to estimate what digital assets might be worth and what would justify their prices. Burniske's first attempt to value Bitcoin happened in 2014 while he was a buy-side analyst at ARK Invest. ARK became the first public fund manager to invest in Bitcoin in late 2015. The fund needed a basis for justifying prices around two hundred dollars, or at least a way to quantify the possibility of substantial appreciation. Other asset managers faced the same need because of their fiduciary responsibilities. This was one reason cryptoasset valuation became important to institutional participants.
An early valuation paper written with Dr. Arthur B. Laffer used several basic ideas: total addressable market (TAM), percentage penetration of that market, velocity (how many times the same asset can be used), and number of coins outstanding. The example used the remittance market. The total addressable market for remittances in 2014 was estimated at four hundred thirty-six billion dollars. Using a present-day TAM to estimate future adoption was identified as a mistake. If Bitcoin's blockchain captured ten percent of that market, it would need to handle forty-three point six billion in transactions. Without a timeframe for adoption, it was impossible to calculate an annual percentage return.
The same Bitcoin could be used more than once in the transmission of value. The example assumed one point five uses per year, which was later considered too low.
Dividing forty-three point six billion by one point five produced a required stored value of approximately thirty billion dollars. At the time, fourteen point seven million coins were outstanding. Dividing thirty billion by fourteen point seven million produced an estimated value of two thousand dollars per Bitcoin. Using the number of coins outstanding at the time of publication for a future adoption scenario was also identified as a mistake. The same framework could be applied to additional markets. Each market could have its own TAM, penetration rate, and velocity assumption. The resulting values could be added together because multiple markets could create overlapping demand for the same limited supply. The exercise also exposed how uncertain the variables were.
The Equation of Exchange Approach
Cryptoassets aren't companies and don't have conventional cash flows. A discounted cash flow analysis isn't directly suitable for valuing them. A cryptoasset model can still use a structure similar to a DCF with annual projections, but the model substitutes the equation of exchange for revenue, margins, and profits. The equation estimates current utility value, and future utility value is then discounted back to the present.
The model uses the equation: M V equals P Q. The variables are interpreted as follows: M is the size of the asset base or monetary base. V is the velocity of the asset. P is the price of the digital resource being provisioned. Q is the quantity of the digital resource being provisioned. The central relationship is that a cryptoasset valuation is largely comprised of solving for M, where M equals P Q divided by V. M is the size of the monetary base necessary to support a cryptoeconomy of size P Q at velocity V.
P does not represent the price of the cryptoasset. It represents the price of the resource being provisioned by the network. In a Filecoin example, P would be the price per gigabyte of storage, expressed as dollars per gigabyte. Q would be the number of gigabytes provisioned. Multiplying dollars per gigabyte by gigabytes produces a dollar amount representing the value exchanged for cloud storage and any other utilities the network might provide.
Hence, the GDP of a cryptonetwork is represented by the on-chain transaction volume of its cryptoasset.
This analogy has limitations. More than thirty percent of a cryptoasset's on-chain transaction volume may sometimes consist of transfers between exchanges. Such transfers don't represent the exchange of value for the network's digital resource and may instead be speculative activity. Foreign exchange volume is similarly not included in the GDP of a nation-state. Second-layer scaling solutions may also make the on-chain measure conservative because some activity occurs off-chain. Assets used in second layers might be treated as bonded assets.
Velocity and the Asset Base
Velocity describes how many times an asset changes hands during a specified period. The equation can be rearranged to calculate velocity: V equals P Q divided by M. Bitcoin in 2016 was used as an example. The network processed an estimated average of one hundred sixty million dollars in USD-denominated transaction value per day, or approximately fifty-eight billion for the year. The average size of Bitcoin's asset base during 2016 was eight point nine billion dollars. The resulting velocity was fifty-eight billion divided by eight point nine billion equals six point five.
A velocity of six point five means the average bitcoin changed hands six point five times during the year. The actual distribution would have been uneven. A small percentage of bitcoin could have changed hands many times, while a larger percentage remained in the hands of long-term holders, or hodlers. For comparison, the velocity of the USD M1 money stock was described as five point five at the time of the analysis. The analysis noted that M1 velocity had declined sharply since the 2008 financial crisis because the monetary base increased while P Q grew only modestly.
The use of an average asset base is important because cryptoasset supplies can expand. This is especially relevant for younger cryptoassets that might experience annual supply increases above twenty percent and could be classified as hyper-inflationary. A valuation model must account for changes in the monetary base rather than treating today's supply as fixed forever. Discount rates are another central component. Assets are priced based on future expectations, and a future utility value must be discounted to derive a present value.
Assets are priced based on future expectations, and to deduce a present value from future expectations one needs discounting.
Unlike a conventional DCF, the crypto model didn't discount a series of annual cash flows. It discounted a single future utility value associated with a selected holding period. The discount rate also represented the expected rate of return required for holding a risky early-stage network.
A Fictional Token Example: INET
The valuation analysis used a fictional bandwidth token called INET. INET was designed to take share in the provision of bandwidth through a decentralized virtual private network. The model was presented as a way to understand the value levers within a token's cryptoeconomic system, not as a conventional equity-style price target. The granularity of cryptoeconomics wasn't yet sufficient for precise price targets, and crypto markets weren't yet efficient enough for asset managers to rely entirely on rational market pricing.
The model was described as useful for developers because it could help them think through the monetary policy of a network before launch. The spreadsheet model had four broad sections: Section A calculated the number of tokens in the float. Section B quantified the protocol economy through the equation of exchange. Section C projected the percentage of the target market captured by the network. Section D discounted future utility values back to the present.
Section A estimated how many tokens would be in circulation and available to the INET economy. The key output was the number of tokens in float after bonders and hodlers. The assumed initial ICO distributed seventy-five percent of all INET tokens that would ever exist, or seventy-five million tokens. Those tokens were assumed to have instant liquidity. The remaining twenty-five million tokens were locked by early private investors, the foundation, and the founders. Two important inputs were the percentages of tokens held by bonders and hodlers. Bonders would be expected to lock tokens to support network security or operation. Hodlers would hold tokens in anticipation of higher purchasing power or a future increase in price.
Proof-of-Stake and other consensus experiments were expected to increase the amount of bonding required from nodes. A bond would incentivize a node to behave properly or lose its stake. Second-layer systems such as Lightning or Raiden were also expected to bond the underlying asset because they facilitate secondary economies off-chain. Bonders and hodlers would remove tokens from the active float. Those tokens would have a velocity of zero in the model because they wouldn't circulate as a means of exchange for the network's digital resource.
Value Capture: Blockspace vs Applications
A 2024 analysis by Michael Dempsey examined expected value in crypto and the supply of blockspace. It referred to three earlier arguments: Fat Protocols, Thin Applications, and Crypto Tokens and the Coming Age of Protocol Innovation. The fat protocol thesis held that value could accrue to base-layer protocols. It also produced a long-tail dynamic among decentralized applications. From a probability-of-success perspective, that dynamic could mean many tokens would be worth something while only a few would go to zero.
The analysis argued that bull markets, and perhaps crypto generally, had changed how builders calculate expected value. Many builders came to see launching a new L1 or L2 as offering the maximum expected value rather than building a decentralized application or application-centric protocol. This encouraged further fragmentation and a plentiful supply of useless blockspace. Builders then created abstractions such as liquid staking tokens to siphon value from L1s and L2s. Data showed that L1s and L2s accounted for the majority of cumulative economic value capture in crypto. The analysis referred to massive fully diluted valuations for networks such as Ethereum, unnamed zombie L1s, and dominant L2s such as Arbitrum.
The utility conclusion was more complicated. A review of trailing 365-day fees across protocols using Token Terminal showed that several DeFi protocols generated more fees than much higher-valued blockspace systems. The analysis said fees weren't a perfect measure of value. Defensibility, terminal scalability, net profitability, and a token's ability to capture a stream of capital were also determinants. A proposal to turn on UNI fee accrual served as an early test of whether governance tokens with little direct fee capture could be revalued if they became connected to tangible value. A number of DeFi protocols traded upward together as the market reassessed the likelihood that valueless governance tokens could capture economic value.
Three Possible Futures for Value Capture
- An effective duopoly or oligopoly of base chains, similar to how mobile consolidated around iOS and Android
- A fragmented ecosystem combining decentralized and centralized systems with application-specific chains
- Continued issuance of high-FDV blockspace tokens under new narratives because speculation and money remain available
The analysis argued that longer-term and more sophisticated token lockups were needed. It noted the recurring agreement that lockups should be extended, followed by limited change in practice. Longer lockups would give retail users and the wider community several years to sell tokens before founders and investors could capture the full value. The mechanism could discourage the launch of the hundredth L1. Applications would also need to plan for longer product-development cycles and more sustainable value capture rather than relying on short-lived shooting star products.
THE DEFINITION OF INSANITY IS DOING THE SAME THING OVER AND OVER AGAIN AND EXPECTING DIFFERENT RESULTS.
Stablecoins as Practical Digital Currency
A stablecoin is a programmable digital currency designed to maintain a more consistent value than many other cryptoassets. Stablecoins are most commonly pegged one-to-one to a fiat currency such as the U.S. dollar or euro, although they may also be linked to commodities, other cryptocurrencies, or U.S. Treasury instruments. They are primarily issued on networks such as Ethereum and Tron. A late 2024 Chainalysis overview described stablecoins as representing more than two-thirds of the trillions of dollars' worth of cryptocurrency transactions recorded in recent months. Unlike most cryptocurrencies, stablecoins are designed to avoid the dramatic price swings associated with assets such as Bitcoin and Ether.
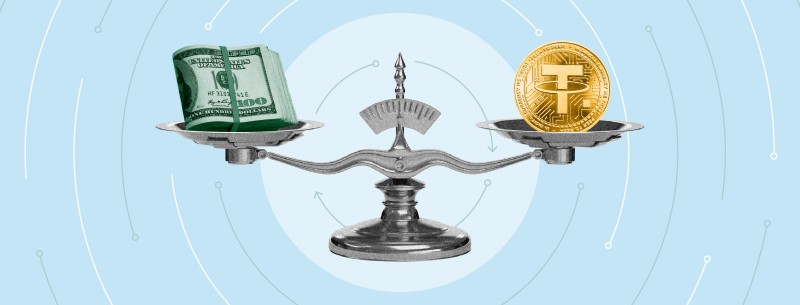
Bitcoin launched in 2009 and introduced a decentralized peer-to-peer transaction system that didn't require intermediaries. Its limited supply and speculative trading dynamics produced extreme price volatility, making BTC difficult to use as a medium of exchange. Ethereum later expanded on Bitcoin's foundation by adding programmability through smart contracts. That innovation helped enable decentralized finance, but ETH also experienced substantial price volatility. Stablecoins first appeared in 2014. They combined blockchain characteristics such as transparency, efficiency, and programmability with a design intended to reduce crypto price volatility. This combination made them useful beyond trading and speculation and appealed to retail and institutional users.
Types of Stablecoins
- Fiat-pegged: tied 1:1 to traditional currencies like USD or EUR, backed by reserves (USDT, USDC, EURS)
- Commodity-pegged: tied to physical assets like gold (PAXG, XAUT)
- Crypto-backed: backed by reserves of other cryptocurrencies, often overcollateralized (DAI)
- U.S. Treasury-backed: supported by Treasury securities and repos, can provide yield (USDY, USYC)
- Algorithmic: maintain value through programmed mechanisms adjusting supply (AMPL, FRAX, USDe)
Stablecoins provide a medium of exchange, a store of value, and a bridge between traditional finance and crypto. They're important liquidity providers for DeFi, centralized exchanges, and cross-border payments. The stablecoin market had matured enough for stablecoins to overtake Bitcoin as a preferred asset for some everyday transactions. Latin America and Sub-Saharan Africa were described as regions where stablecoins were being used as a hedge against local monetary instability. Retail adoption was driven by low-cost remittances, secure savings in regions with volatile currencies, and access to DeFi services such as lending and staking.
One comparison found that sending a two hundred dollar remittance from Sub-Saharan Africa using stablecoins was approximately sixty percent cheaper than using traditional fiat-based methods. Stablecoins can function as a store of value where economic instability or inflation is high. Pegging to the dollar or another stable asset can help preserve purchasing power and protect funds from local-currency volatility. In emerging markets with limited access to stable financial instruments, stablecoins can provide a straightforward route into U.S.-dollar-linked value.
Institutional Adoption and Financial Infrastructure
A 2026 forecast predicted that the technical and regulatory groundwork laid over previous years would begin to produce fuller institutional adoption. Trusted digital-asset infrastructure and expanded utility were expected to move banks, corporations, and providers from pilot programs into production. The prediction focused on four areas: stablecoins, on-chain assets, crypto custody, and automation through artificial intelligence.
The forecast predicted that stablecoins would be fully integrated into global payment systems within five years. They would become foundational payment rails rather than merely an alternative to existing systems. It cited Visa and Stripe as institutions connecting these rails to incumbent payment flows. The forecast described the passage of the GENIUS Act as inaugurating a digital-dollar era. It stated that highly compliant, U.S.-issued stablecoins, including Ripple USD (RLUSD), would become standards for programmable, 24/7 global payments and collateral in modern financial markets.
By 2027, the forecast expected financial institutions to use regulated stablecoins for 24/7 collateral mobility in capital markets. It argued that business-to-business payments, rather than retail use, would be the main growth engine. B2B stablecoin payments had reached an annualized run-rate of seventy-six billion dollars in the prior year. In early 2023, monthly B2B stablecoin transfers had been below one hundred million dollars. The forecast also cited more than seven hundred billion dollars in idle working capital on S&P 1500 balance sheets and more than one point three trillion euros across Europe. It argued that stablecoins could provide real-time liquidity, reduce carrying costs, and improve cash-flow efficiency.
Institutional Adoption Signals
- 60% of Fortune 500 companies actively working on blockchain initiatives (2025 survey)
- More than 200 public companies holding Bitcoin as part of treasury strategies
- Digital-asset-treasury companies grew from 4 in 2020 to more than 200
- More than 40 crypto ETFs launched in 2025, representing only 1-2% of total U.S. ETF market
- Custody becoming commoditized, driving consolidation and vertical integration
The forecast predicted increasing convergence between blockchain and AI in financial operations. Stablecoins and smart contracts could allow treasuries to manage liquidity, execute margin calls, and optimize yield across on-chain repurchase agreements in real time without manual intervention. Asset managers could combine AI models with blockchain infrastructure to rebalance exposure to tokenized assets and stablecoin yield protocols. Zero-knowledge proofs were expected to allow AI systems to assess creditworthiness or risk without exposing sensitive data.
Regulation and Political Influence
A 2026 commentary argued that cryptocurrency had become openly political. The author described two decades of arguments between crypto advocates and supporters of state governance, stating that crypto advocates had increasingly become part of government and political influence networks. Political power had previously been associated with Wall Street, Big Oil, or Big Tech. Crypto money and artificial intelligence were described as emerging power bases with trillions of dollars in capital.
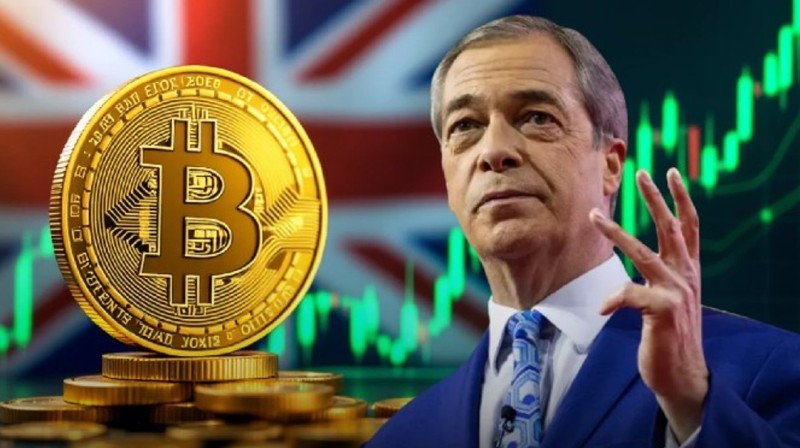
In Britain, Nigel Farage was described as positioning himself as a major pro-crypto figure in mainstream politics. He openly associated with Bitcoin investments and digital-asset advocates. Reform UK was described as increasingly comfortable attracting support from wealthy crypto entrepreneurs who viewed the sector as an ideological movement favoring lower taxes, lighter regulation, and reduced state control. In the United States, crypto political action committees were described as holding war chests measured in hundreds of millions of dollars. They funded candidates, attacked opponents, and helped shape legislation.
The commentary described the strategy in direct economic terms: if regulation determines the future value of digital assets, influencing regulators becomes another investment strategy. Donald Trump was described as moving from skepticism about Bitcoin to becoming one of the crypto industry's most significant political beneficiaries. His rhetoric shifted toward making America the crypto capital of the world. The commentary connected this change to Elon Musk, Mark Zuckerberg, and other technology figures who supported his 2024 re-election and were major donors during that campaign.
Trump and his family were described as embedded in the industry through World Liberty Financial, a crypto platform connected to the family that spans token sales, decentralized finance, and stablecoins. The venture was described as generating substantial revenue and attracting scrutiny over possible conflicts of interest because political power and commercial crypto interests were becoming intertwined. The commentary contrasted the older model, in which politicians were funded by industries, with a newer model in which politicians become industry participants.
Security Failures and DeFi Lending Runs
A 2026 Bank Policy Institute analysis examined a hack and subsequent run in decentralized finance. On April 18, 2026, hackers were estimated to have stolen two hundred ninety million dollars from major DeFi lending platforms. The losses exposed lenders to potential financial harm. Aave, the largest DeFi lending platform, experienced mass withdrawals, and some lenders, including stablecoin lenders, were unable to withdraw their funds.
The analysis identified three risks inherent in DeFi lending: platforms may receive inaccurate information from third-party sources; insurance funds may not contain enough capital and liquidity to compensate lenders after losses; mixers can obscure wallet-holder identities and make it harder to detect criminal activity. The analysis argued that these risks persisted because of inadequate regulatory and supervisory standards.
The KelpDAO exploit involved a restaking protocol. A user deposited an Ethereum token (ETH) and KelpDAO staked it to generate rewards. The receipt for the staked ETH was a token called rsETH. The receipt could be traded or pledged as collateral on other crypto platforms. KelpDAO used a bridge service called OFT. Bridges allow cryptoassets to move between blockchains. The hackers exploited a vulnerability that allowed them to create rsETH tokens without providing the corresponding ETH. They pledged the fabricated rsETH as collateral on DeFi lending platforms and borrowed legitimate ETH. KelpDAO froze markets related to rsETH after discovering the problem. Lending platforms then recognized rsETH as worthless. Lenders who had provided ETH received worthless rsETH collateral, while the hackers retained the borrowed Ethereum.
The KelpDAO exploit led to a run on Aave as lenders attempted to redeem ETH they had lent. Aave normally reimburses lenders for counterparty losses through an insurance fund. However, the size of the losses caused investors to fear that the fund would not be sufficient. The value of Aave's insurance fund was estimated at eighty million to one hundred million dollars, while potential exposure was almost two hundred million dollars. Aave allowed a lender to withdraw a lent token only if some tokens remained idle in the relevant liquidity pool. After substantial withdrawals, lenders could no longer withdraw their ETH because the pool had insufficient idle ETH. The situation was compared to bank depositors being unable to withdraw account balances during a bank run.
The run spread beyond ETH lenders. Only ETH lenders were directly exposed to the rsETH losses, but lenders of other cryptoassets also withdrew because they feared becoming unable to retrieve those assets. Approximately five billion dollars in stablecoins was withdrawn from Aave shortly after the hack was announced. Demand for stablecoin borrowing increased while the supply of stablecoin funding decreased. Stablecoin interest rates rose to around ten percent. Similar events in the past caused interest rates on DeFi platforms to rise. In October 2021, a hacker drained one hundred thirty million dollars from Cream Finance. In July 2023, a hack on Curve Finance caused its token price to fall sharply.
Product-Market Fit Without the Ideology
A 2023 QED Investors post argued that people use crypto products because of product-market fit and value, not primarily because of libertarian, anarchist, or ideological commitments. The post responded to a piece by Scott Alexander and focused on people who had not fully formed a view of crypto. The post highlighted a space analogy: the space program has been for more than fifty years, and mostly succeeded at reinventing things we already have on Earth, only worse. The only excuse is: yes, but it's in space. In the same way, everything about the crypto economy is worse than the regular economy. The only excuse is that it's decentralized. This means you can use it for all of those cool things - sending remittances, circumventing corrupt banking systems, resisting authoritarian governments - that are hard to do with regular money.
The QED post disputed the claim that everything about crypto was worse. It described binary positions as simple but incomplete because the relevant information was in the gray area. It identified tangible advantages such as faster settlement, lower cost, and borderless operation. The post also listed non-economic characteristics including transparency, trustlessness, self-custody, permissionlessness, distribution, digital property, and attack resistance. It said these characteristics were often overlooked when observers focused on the scoreboard of products, users, transaction volume, and market capitalization.
Consumers didn't need to use decentralized, open, or self-custody products to receive value. Many top consumer applications were centralized companies, including Binance, Coinbase, and OpenSea. At the time of the post, ranks three through seven among the top tokens by market capitalization were described as centralized. The top three stablecoins were centralized and represented more than ninety percent of total stablecoin market capitalization. Bitcoin mining was also described as centralized and consolidating, with some mining operations associated with large energy companies.
The central claim was that people were using products because they solved practical problems.
The post compared crypto and blockchain to extending highly productive urban real estate into the sky. The analogy was a floating version of New York, San Francisco, and Los Angeles above the clouds. Those cities could extend finance, internet technology, and media into a parallel economic layer with capabilities that blockchain and tokenization could provide. In that layer, blockspace would be the equivalent of real estate, applications would be businesses operating on top of it, and tokens would provide a standardized way to represent a broad spectrum of assets.
The post argued that new cities and industries in this parallel layer would contribute to GDP and employment that might not otherwise exist. It described the combined economy as positive-sum because it wouldn't directly compete with existing real estate. Crypto was described as a new frontier that could provide the inspiration previously associated with large public projects and space exploration. The post compared it to a distributed Manhattan project undertaken without a war or a central government coordinating the effort. It argued that talent was entering crypto because it offered an exciting and genuinely new field.
What Drives Real Adoption
- Faster settlement and lower cost than traditional rails
- Borderless operation without permission
- Transparency and auditability of on-chain activity
- Self-custody option for those who want it
- Digital property rights that survive platform changes
The post described crypto without the crypto terminology as an exciting parallel economic layer with product-market fit, positive-sum potential, and novel or breakthrough technology. It said that, at the margin, more of these projects were needed rather than fewer. When you look at what market cap actually tells you across the top tokens, you see a mix of protocols, applications, and stablecoins all capturing value in different ways. The top twenty by market cap list changes every cycle but the pattern stays similar: infrastructure-heavy at the top, applications fighting for share below. If you're wondering what cryptocurrency actually means in practice, it's not about ideology. It's about whether the product solves a problem someone has today. Some people ask how to launch a token thinking the tech is the hard part. The hard part is finding product-market fit. Others ask where to start with crypto investing and get lost in narratives. The signal is in the usage, not the story.
Comments on “How Crypto Value Gets Decided and What It Actually Means for You”
No comments yet. Be the first to share your thoughts.